Mochi Health vs. Big Easy Weight Loss
Same compounded GLP-1s. Lower monthly cost. More care.
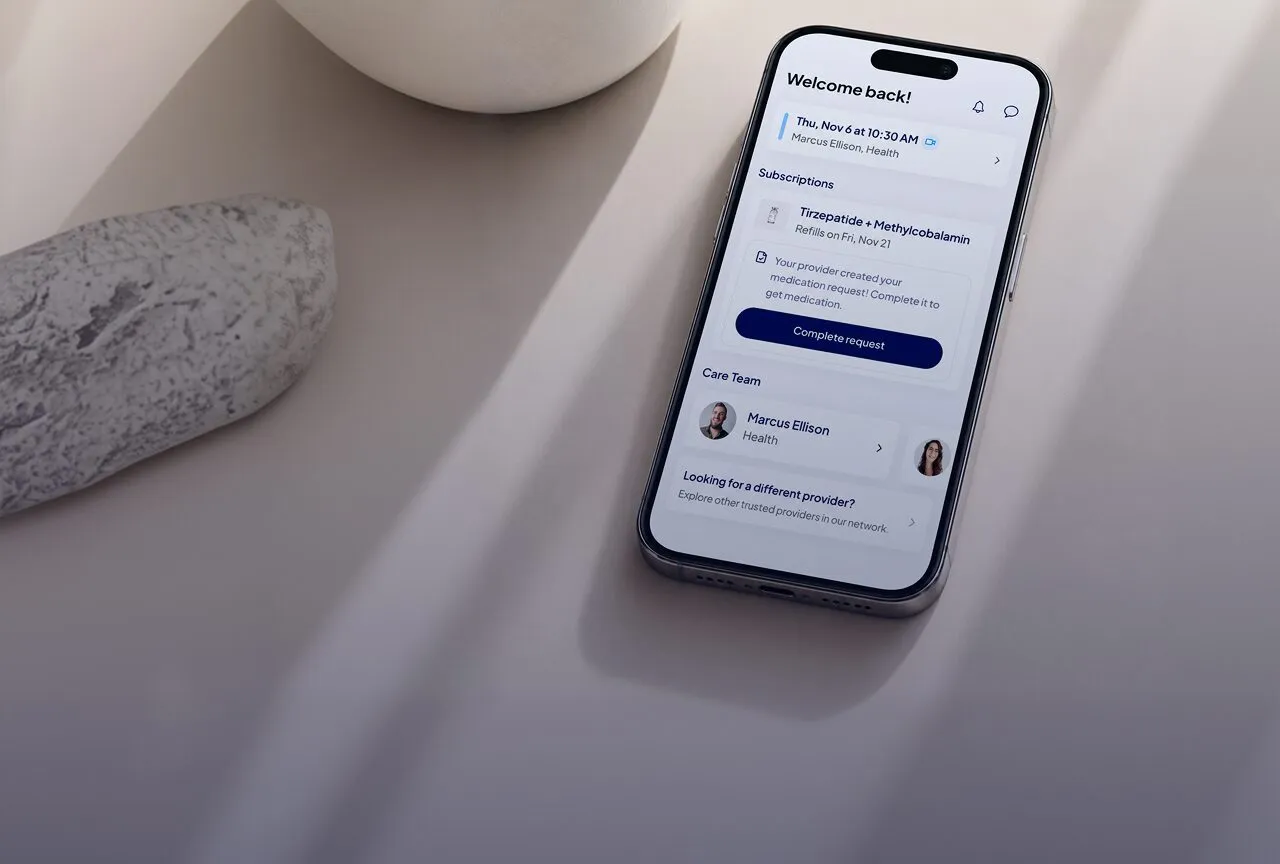
Big Easy Weight Loss sells 8–12 week packages with $75 due up front. Mochi Health is month-to-month: first month free, then $79, with unlimited 1-on-1 video visits, dietitian support, and insurance billing.
Pricing, side by side
Mochi Health
$0 first month, then $79/mo
Semaglutide from $60/mo
Tirzepatide from $90/mo
No consultation fee, no prepay, cancel anytime
Or use insurance: $17/mo billed annually + copays ($0–$30), dietitian visits $0
Big Easy Weight Loss
$75 consultation due up front
Semaglutide from $495 per 12 weeks (~$165/mo)
Tirzepatide from $469 per 12 weeks (~$156/mo)
8–12 week packages, cash pay only (no insurance option)
Feature by feature
Price is only half the question. This is what is included on each side.
Where Mochi Health pulls ahead
Unlimited visits, not a single consult
Unlimited 1-on-1 video visits and dietitian sessions are included. Big Easy charges $75 for the initial consult, then bundles care into a fixed package.
Use the insurance you already pay for
Mochi bills your doctor visits in-network: copays typically $0–$30 and dietitian visits $0. Big Easy does not bill insurance.
No 12-week commitment
Start free and stay month to month. Big Easy's prices cover 8–12 week courses paid up front.
Medication priced separately, and lower
Compounded semaglutide from $60/mo and tirzepatide from $90/mo, billed separately. Branded options like Wegovy and Zepbound are available too.
One membership, more than weight loss
Menopause, hair loss, skincare, longevity, and mental health care all live in one plan. Big Easy focuses on weight loss and regenerative treatments.
Ready to switch?
Your first month is free on the 1-month plan. No consultation fee, no 12-week package, cancel any time.
Big Easy Weight Loss pricing reflects rates published on joinbigeasy.com and is subject to change. Monthly equivalents are calculated from the advertised package price. Compounded medications are prepared by licensed 503(a) or 503(b) pharmacies and are not approved by the FDA. Insurance coverage, eligibility, and copays vary by plan.